Changing Consumer Diets Alter Agriculture

June 16, 1992

PAER-1992-12

Chris Hurt

Consumers in the United States con­tinue to alter their diets. As they change the types of food products they eat, the food system must adjust to meet these desires. The figure at right shows some of the basic changes which are taking place in per capita consumption of selected food products. The percentage changes shown in the figure are for 1990 compared to 1983.

Consumers have reduced consumption of products they consider to be high in saturated fats or cholesterol, such as whole milk, ice cream, eggs, and red meats. One exception to the reduction of saturated fats is cheese, where consumption has risen about 20%, presumably because of our increased taste for pizza. Alternatively, con­sumers have increased consumption of vegetables. fish and seafood products, grains, low-fat milk, and poultry. Increases are especially noted in consumption of fresh products such as fresh fruits and vegetables.

These changes have important implications for the entire food system, from farmers to grocery store managers/ Farmers must grow the type of raw food products which processors can convert to the final food products consumers desire. Participants in the food system who can meet these needs stand a greater chance of financial reward, while those who do not, stand a greater chance of receiving low economic returns over time.
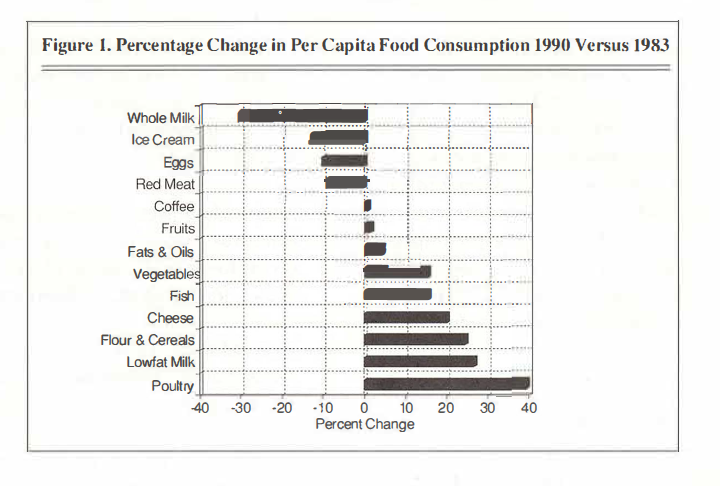
 

Figure 1. Percentage Change in Per Captia Food Consumption 1990 Versus 1983
Figure 1. Percentage Change in Per Captia Food Consumption 1990 Versus 1983

Tags

Publication Appeared Within:

Latest Articles:

The August 2026 CPI and PPI Reports: The Late-July Energy Spike Arrives, and the Food Pipeline Still Holds

September 16, 2026

Energy costs surged across both reports this month — diesel fuel up 24.1 percent, gasoline up 3.9 percent — in a single month. At the same time, food inflation sat almost exactly where it sat in July, and the most upstream producer-price stage swung through a wider range than the stage nearest the consumer has moved in three months combined. A real, measurable energy shock landing squarely in the data, alongside a food pipeline that barely moved, is the sharpest evidence yet for the thesis this series has been building since spring.

The August 2026 Beef Import Waiver: A Narrow Tool Aimed at a Narrow Problem

August 25, 2026

This is a targeted policy aimed at a narrow slice of the beef market — imported product for ground beef, much of which is lean processing beef — rather than a broad intervention in the fed-cattle market. It was announced in response to historically tight cattle supplies and unusually high beef prices. Within that narrow lane, the most plausible effect is some additional availability of lower-cost processing beef and some downward pressure on ground-beef prices.

The July 2026 CPI and PPI Reports: The Energy Shock Bypasses the Food Pipeline

August 20, 2026

Energy prices are 14.7 percent above year-ago levels, and yet the raw agricultural commodities that sit at the head of the food pipeline are cheaper than they were last July. That combination is the whole story of this month’s release — but it is not evidence that the energy shock missed agriculture.