September 2, 2026
Why U.S. Farmers Own Farmland and What They Expect for Land Values
by Michael Langemeier and Joana Colussi


Farm operators own farmland for many reasons, including current income, long-term investment, and family or sentimental reasons. Using results from the August 2026 Purdue University-CME Group Ag Economy Barometer (AEB) survey, which included responses from approximately 400 U.S. farmers, this article examines reasons for owning farmland, factors influencing farmland values, and how producers perceive farmland as an investment. To facilitate comparisons, respondents were grouped into two categories: crop producers and livestock producers. Approximately one-third were classified as livestock producers, meaning they derived more than 50% of their farm revenue from livestock production.
n August, the AEB index increased to 135, indicating that average sentiment was more positive than during the index’s base period, which includes the fourth quarter of 2015 and the first quarter of 2016. The AEB index is subdivided into two sub-indices: the Index of Current Conditions (ICC) and the Index of Future Expectations (IFE). Index values for August 2026 were 123 for the ICC and 140 for the IFE (Langemeier and Colussi, 2026).
Reasons for Owning Farmland
The August AEB survey asked respondents: “Think about the farmland that you own. What is your primary reason for owning this farmland?” Results are presented in Table 1. Family or sentimental reasons were the most frequently cited motivation, selected by 45% of respondents. Long-term investment ranked second at 32%, while current income was selected by 22%. These results suggest that farmland ownership is often motivated by considerations that extend beyond annual financial returns.
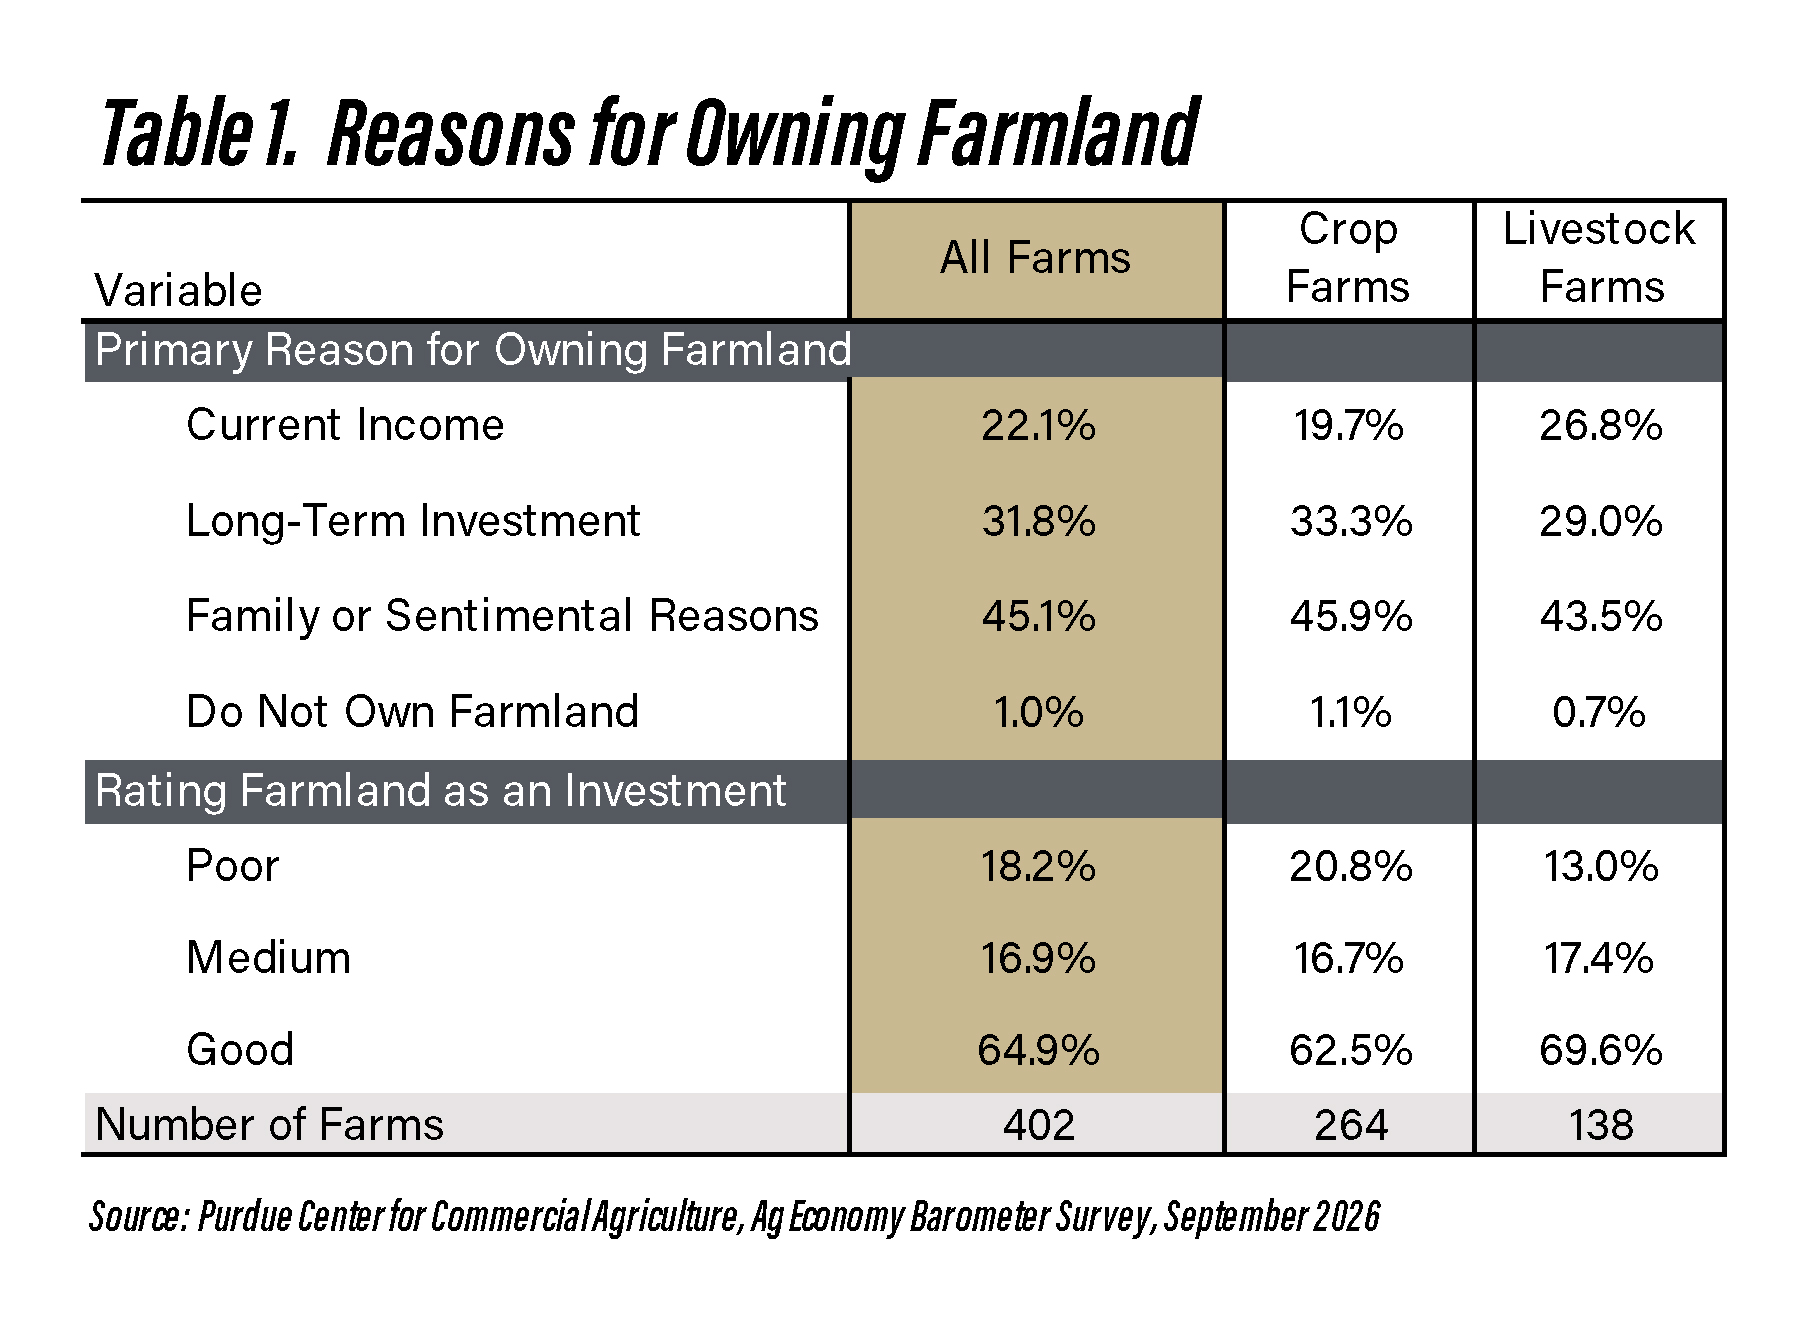
Table 1. Reasons for Owning Farmland
For comparison, Tong and Zhang (2023) asked a similar question in a 2022 Iowa landowner survey. In that survey, 38% of landowners identified current income as their primary reason for owning farmland, 23% selected long-term investment, and 37% selected family or sentimental reasons. Family or sentimental reasons ranked highly in both surveys, but AEB respondents were less likely to identify current income and more likely to identify long-term investment as their primary motivation. The comparison should be interpreted cautiously because the two surveys represent different populations. The Iowa survey focused broadly on landowners, whereas the AEB survey focuses on agricultural producers.
Periodically, the AEB survey asks respondents to evaluate farmland as an investment. Consistent with previous survey results, approximately two-thirds of respondents indicated that farmland is a good investment.
Expectations and Factors Influencing Farmland Values
Table 2 presents characteristics and measures of producer sentiment for the full sample, crop producers and livestock producers. In contrast to the producer sentiment of livestock farms, sentiment regarding future expectations for the crop farms was higher than sentiment regarding current conditions. In addition, a higher percentage of livestock farms expect farmland values to be higher 12 months from now. In contrast, a lower percentage of livestock farms expect farmland values to be higher 5 years from now. In general, producers are more optimistic regarding farmland values 5 years from now than they are regarding land values 12 months from now.
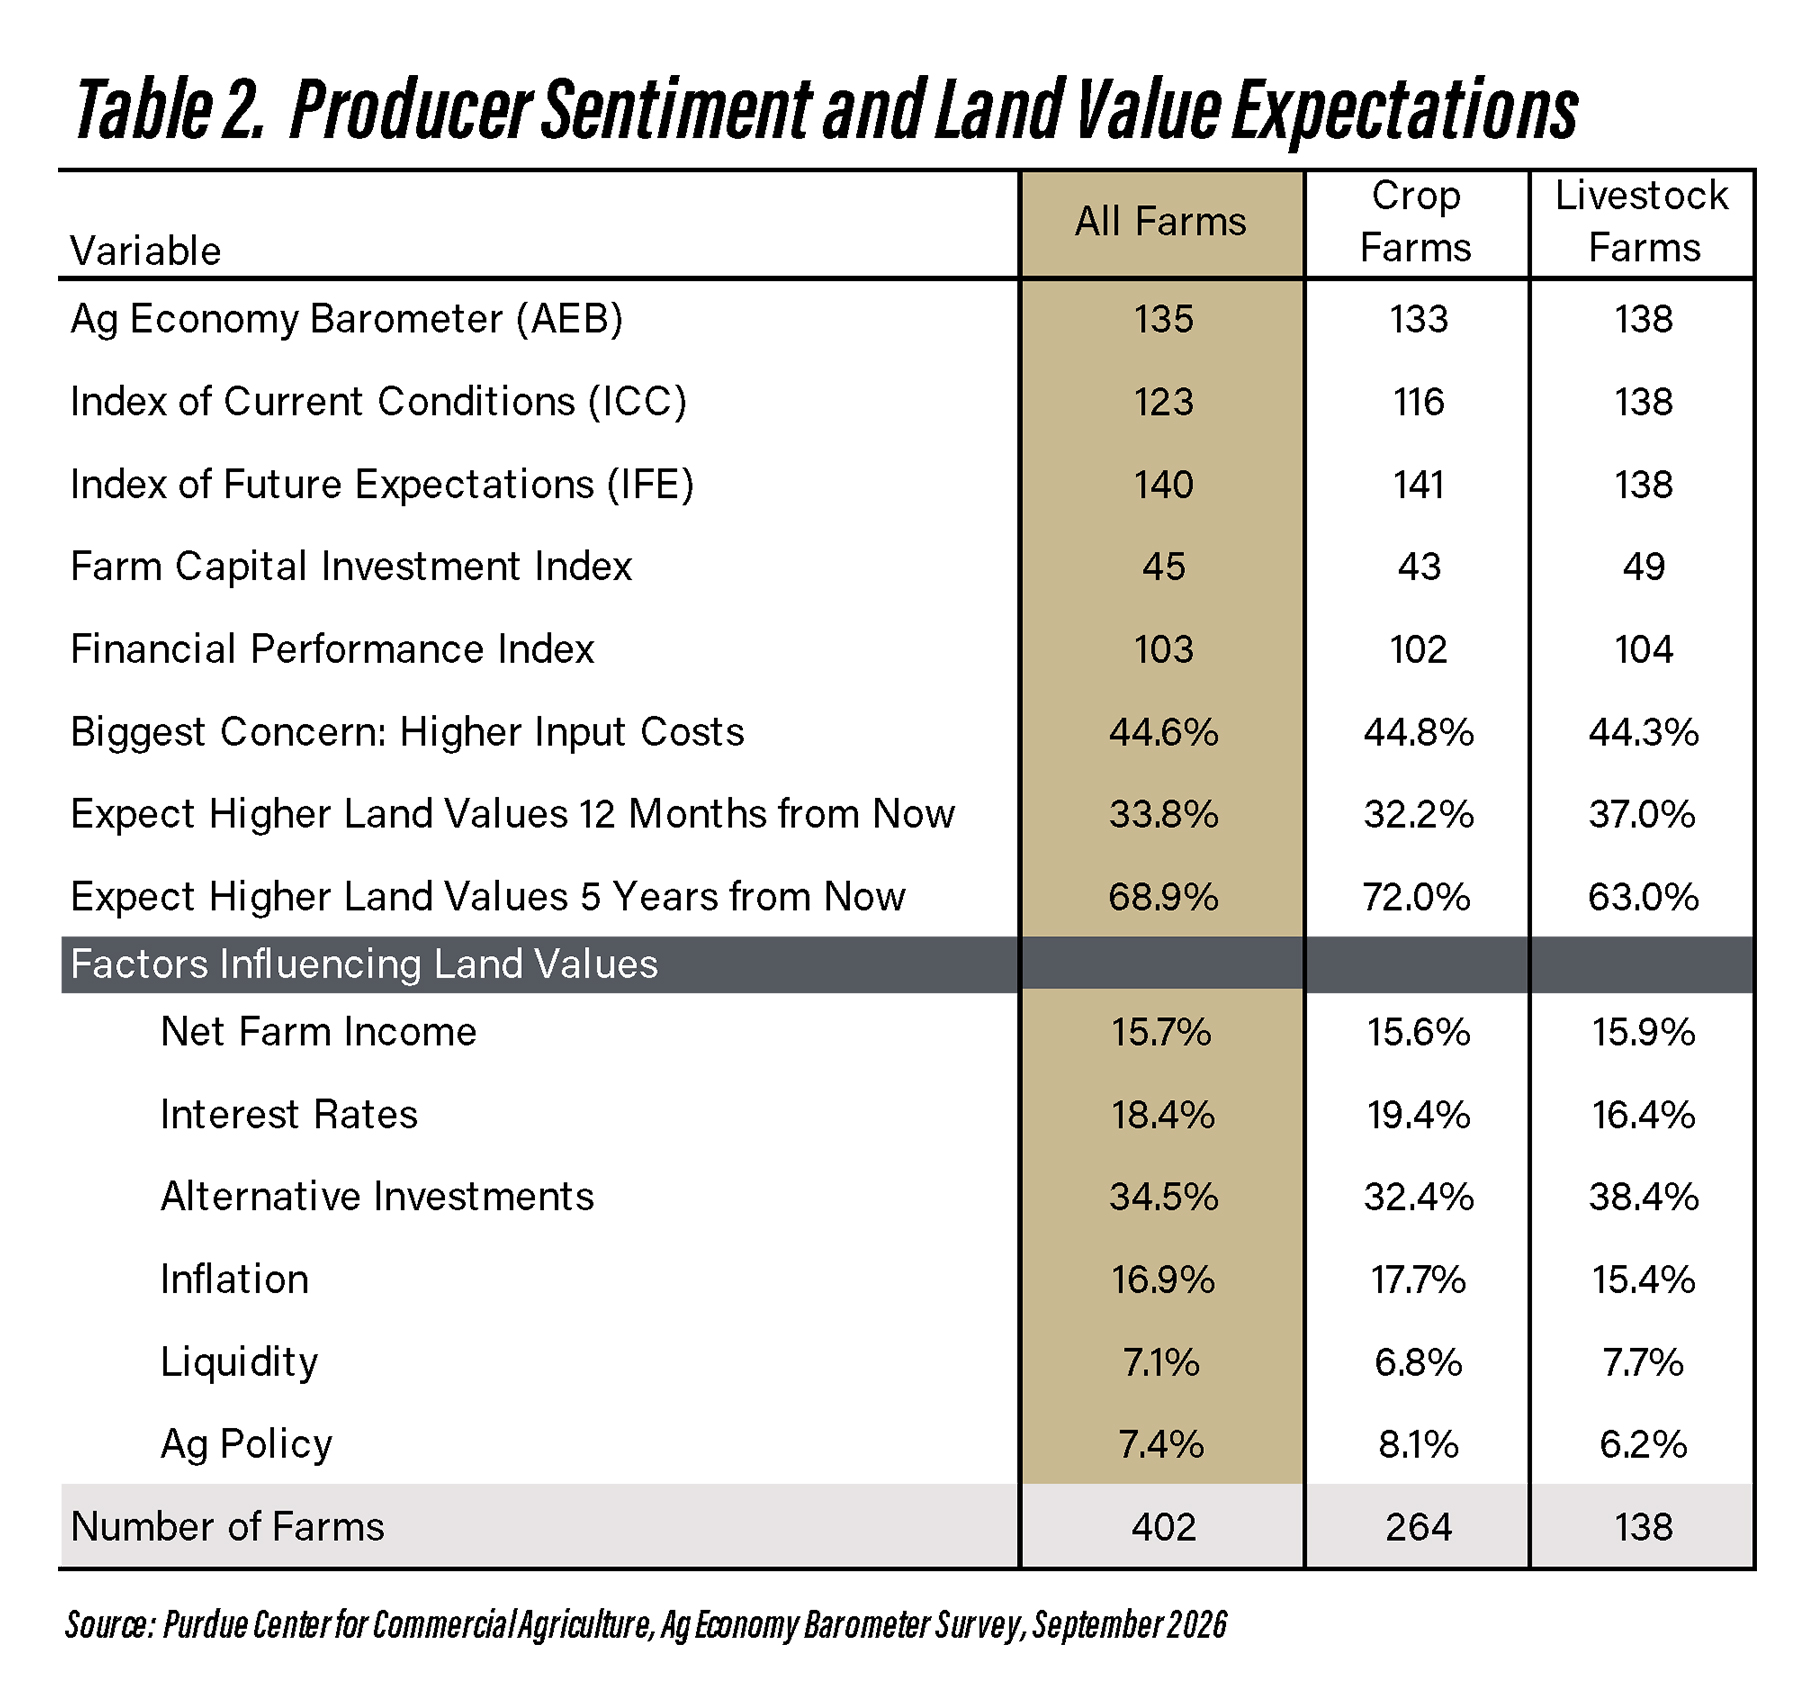
Table 2. Producer Sentiment and Land Value Expectations
Another monthly AEB survey question asks respondents to indicate which of the following factors is having the most influence on farmland values in their area: net farm income, interest rates, alternative investments, inflation, liquidity, or agricultural policy. Respondents are not asked whether each of the six factors has a positive or a negative influence on farmland values. Alternative investments ranked as the most influential factor among both crop and livestock producers, followed by interest rates. The third most important factor was inflation for the crop farms and net farm income for livestock farms.
Farm Investment, Financial Performance, and Concerns
The Farm Capital Investment Index measures whether respondents think it is now a good time or a bad time to make farm investments, including items such as machinery and buildings. An index below 100 indicates that more respondents believe it is a bad time than a good time to make such investments. The Farm Capital Investment Index was 43 for crop farms and 49 for livestock farms. The higher index among the livestock farms is consistent with their higher sentiment regarding current conditions.
The Financial Performance Index measures whether a farm expects its financial performance to be better than, worse than, or about the same over the next 12 months. An index below 100 indicates that more farms expect their performance to be worse rather than better in the next 12 months. The average index for August was 103. Another monthly AEB question asks respondents to identify the biggest concerns for their farm, using the following response choices: lower crop and/or livestock prices, high input costs, environmental policy, farm policy, interest rates, and availability of inputs. High input costs were the biggest concern for both groups of farms. Approximately 45% of respondents indicated that input costs were their biggest concern.
Final Considerations
Results from August 2026 Ag Economy Barometer highlight that farmland ownership is motivated by more than current financial returns. Family or sentimental reasons were the primary motivation for 45% of respondents, while another 32% identified long-term investment as their main reason for owning farmland. Only 22% selected current income.
These motivations are consistent with producers’ broader views of farmland as an asset. Approximately two-thirds of respondents indicated that farmland is a good investment, and producers were considerably more optimistic about farmland values over the next five years than over the next 12 months. Alternative investments and interest rates were identified as the two most influential factors affecting farmland values.
The analysis suggests that farmland continues to play a unique role for U.S. farm operators. It is not only a productive asset, but also a long-term investment and, for many producers, an asset closely tied to family and generational considerations.
References
Langemeier, M. and J. Colussi. “Farmer Sentiment Rises Again in August as Future Expectations Improve.” Purdue University-CME Group Ag Economy Barometer, September 1, 2026. Available at: https://ag.purdue.edu/commercialag/ageconomybarometer/.
Tong, J. and W. Zhang. “Iowa Farmland Ownership and Tenure Survey 1982-2022: A Forty-
Year Perspective.” Working Paper 23-WP 651, Center for Agricultural and Rural Development, Iowa State University, August 2023.
TAGS:
TEAM LINKS:
RELATED RESOURCES
UPCOMING EVENTS
Join educators from across the Midwest to build skills for communicating soil health concepts on Nov. 4-5, 2026. In the field, we’ll evaluate the relationship between soil health and water management focusing on irrigation and edge of field practices. The in-service will have both classroom and on farm demonstrations.
The Land of Opportunity: A Conference for Farmland Owners will be held at two locations on October 5 and October 6, providing farmland owners with valuable information and resources to help them make informed decisions about their land. The conference will feature keynote presentations, educational breakout sessions, and networking opportunities designed specifically for those who own, manage, or have an interest in farmland.